Digital Gold Ownership Vs Traditional Gold Savings: A Malaysian Comparison

Malaysians can buy gold digitally and store it professionally, while traditional buyers  still prefer keeping physical bars, coins, or wafers themselves. Both support long-term gold savings, but the responsibility differs. Compare what you own, who stores it, and how you can sell or redeem it.

Digital Gold Vs Traditional Gold Savings: The Short Answer

Neither method is inherently superior; they simply solve different problems. Physical gold gives direct possession but requires secure storage and resale arrangements. Properly backed digital gold offers fractional purchases and professional vaulting, but buyers must verify ownership, custody, costs and redemption terms.

The main difference is how ownership is recorded and who stores the gold.

What Does Digital Gold Ownership Mean?

Digital gold ownership generally means buying gold through an app while the underlying physical bullion is kept by a provider or appointed vault operator. In a physically backed arrangement, your digital account balance represents real gold. Product documents such as Product Disclosure Sheet (PDS) should explain when ownership transfers, how holdings are recorded and who safeguards the metal.

Not Every Digital Gold Product Is The Same

Allocated platforms, bank gold accounts, exchange-traded funds and tokenised products can provide different rights. 

Some represent physical gold ownership; others provide price exposure through a claim or fund unit. Ask “What do I own?”

What Are Traditional Gold Savings?

Traditional physical gold savings involve buying physical bars, coins, or bullion wafers and taking direct personal possession. While gold jewellery is more popular in Malaysia, it typically incurs substantial design and workmanship fees (upah). This makes jewellery less efficient for wealth preservation compared to pure, investment-grade gold bars or coins (such as 999.9 purity bullion). 

Digital Gold Vs Physical Gold Savings At A Glance

Comparison Area

Digital Gold

Traditional Physical Gold

Ownership

Recorded through a platform and defined by its terms

Supported by possession and purchase documents

Starting Amount

Often available in fractional weights

Depends on available bar or coin sizes

Storage

Managed by a provider or vault operator

Managed by the buyer

Insurance

May be arranged by the provider

Arranged by the buyer if required

Selling

Requested through the platform

Requires a dealer or buyer

Partial Selling

Often possible

Limited by the denomination held

Physical Access

Subject to redemption terms

Already in the buyer’s possession

Main Additional Risk

Provider, custodian and operational risk

Theft, loss and authenticity risk

Costs

Spread and possible transaction or redemption fees

Premium, spread and possible storage costs

Both methods remain exposed to gold price movements and the difference between purchase and selling prices.

Where Digital Gold May Have An Advantage

Smaller And More Regular Purchases

Fractional purchases can make a regular gold savings habit more manageable than waiting to afford a particular bar or coin. They do not guarantee better returns, and the gold received depends on the provider’s quoted purchase price.

Professional Gold Vault Storage

Storing gold outside the home can reduce exposure to household theft, loss and accidental damage. Buyers should confirm where the metal is held, who controls it and whether customer holdings are properly recorded. Professional gold vault storage transfers responsibility to specialised parties, so their roles must be clear.

Insurance And Easier Account Management

Vaulted gold is typically covered under comprehensive commercial insurance policies, saving you from purchasing individual home insurance riders. Additionally, a mobile application that lets you track live portfolio values, review transaction histories, and liquidate fractions of your stash instantly during operational hours. 

Where Traditional Physical Gold Have An Advantage

Direct Possession And Control

Physical gold can be accessed without a platform or redemption request. This appeals strongly to buyers who value tangible possession and can manage security themselves.

Less Dependence On A Platform

Once collected, a bar or coin does not depend on an app. The owner still needs a buyer when checking authenticity and selling at the available buyback price. Physical gold can also be gifted directly, although documents should be retained.

What Risks Come With Each Method?

Digital storage does not remove risk. It shifts the storage responsibility from the buyer to the platform, custodian, vault operator and insurer.

  • Digital Gold Risk: You delegate physical storage, shifting risk toward the provider, custodian, vault operator, and insurer. Essential safeguards to check include physical backing ratio, purity guarantees, custody segregation, and asset distribution policies in the event of provider insolvency.
  • Physical Gold Risk: You retain total storage responsibility. Risks include home theft, physical damage (which lowers resale value), or losing original certificates. Utilizing a third-party safe deposit box mitigates theft but adds fixed recurring rental fees. 

Is Digital Or Physical Gold More Shariah-Compliant?

Neither physical nor digital gold is automatically Shariah-compliant by default.. According to the Bank Negara Malaysia (BNM) Shariah Advisory Council (135th Meeting, a valid Islamic gold transaction must fulfil core Shariah parameters: 

  • Contracting Parties: Clear buyer and seller capacity
  • Subject Matter: Real, existing, and deliverable 999.9 gold
  • Offer & Acceptance: Unambiguous agreement 
  • Instant Settlement: Immediate allocation or constructive possession

For digital gold to be Shariah-compliant, the underlying transaction must avoid delayed settlement (Riba al-Nasi’ah)  and ensure real physical gold is allocated immediately upon payment (Qabd Haqiqi or Qabd Hukmi). Always verify that a digital platform features a recognized Shariah advisor and explicit contract structures such as Wakalah or Bai’ al-Sarf .

What Should Malaysians Check Before Choosing?

Check these points before selecting a gold savings method:

  1. Do I own physical gold or receive only price exposure?
  2. When does ownership transfer to me?
  3. What is the gold purity?
  4. Who stores it, and how are holdings recorded?
  5. Is it insured, and what does the policy cover?
  6. What is the purchase and selling spread?
  7. Are there storage, transaction or redemption fees?
  8. Can I redeem bars or coins?
  9. Does the plan restrict access before maturity?
  10. Has the Shariah structure been independently reviewed?

Which Gold Savings Method Suits You?

Physically backed digital gold suit buyers seeking fractional purchases, managed storage and partial selling. Physical gold suits those prioritising possession or gifting. Some buyers use both. Keep emergency money separately because gold prices can fall and selling may take time.

How GoldNow Structures Digital Gold Ownership

GoldNow by Tomei addresses the key requirements of digital gold accumulation through a structured, physically backed model.

Built On Tomei Group’s Gold Heritage

GoldNow extends Tomei Group’s established experience in Malaysia’s gold industry into a digital format. With more than five decades of experience handling gold and a nationwide presence of 60 stores, Tomei provides the operational foundation behind the platform.

This heritage supports important parts of the customer experience, including 999.9-purity gold, secure vault storage and physical redemption through selected Tomei outlets. For customers, the connection to an established gold retailer adds a practical link between the gold recorded digitally and the physical metal supporting their holdings.

  • Fractional Ownership And Physical Redemption

Accumulate pure 999.9 gold starting from as low as 0.1 grams. Full ownership transfers upon purchase with options to keep gold vaulted or requested physical bar redemption.

  • Vault Storage And Insurance

All digital balances are backed 1:1 by real gold stored in secured vaults and fully insured. To safeguard user funds, fiat money awaiting purchases is held in segregated Islamic bank accounts managed by an independent trustee (MTrustee Berhad).

GoldNow states that holdings are backed by real gold, kept in Tomei vaults and insured. Funds awaiting purchase are placed with a licensed trustee in a segregated Islamic bank account. MTrustee Berhad is identified as the independent custodian.

  • Shariah-Compliant Gold Structure

The transaction framework utilizes Wakalah (agency) for platform services and Bai’ al-Sarf (currency / precious metal exchange) for immediate settlement. The structure is independently endorsed by ISRA Consulting, a subsidiary of INCEIF University under BNM

  • Gold Savings Module Terms

The Gold Savings Module has tenure and lock-in terms. Gold in a Savings Pot cannot normally be sold, converted, transferred, gifted or redeemed during the lock-in period unless a stated release event occurs.

Explore Gold Savings With Managed Storage

If fractional ownership and managed storage suit your goals, explore GoldNow. Review its disclosures, fees, redemption arrangements and savings terms before choosing an amount or tenure.

How Physical Gold Redemption Works With GoldNow

GoldNow allows users to convert their digitally accumulated gold into physical gold bars or coins, subject to the available denominations and redemption terms.

Redeem Physical Gold Starting From 1 Gram

Physical redemption starts from 1 gram. Once a user has accumulated at least 1 gram in the GoldNow app, they can submit a redemption request and collect their physical gold from a selected Tomei outlet in Malaysia.

Redemption fees and available collection locations are displayed in the app before the request is confirmed.

FAQs- About Digital And Traditional Gold

Is It Better To Own Physical Gold Or Digital Gold?

Physical gold gives direct possession but requires secure storage. Properly backed digital gold offers fractional purchases and managed storage, but its ownership, custody, insurance, costs and redemption conditions must be verified.

What Are The Advantages Of Buying Digital Gold?

Digital gold can offer fractional purchases, professional vault storage, insurance and easier account management. Depending on the provider, customers can monitor holdings, sell smaller amounts and redeem physical gold without storing every purchase at home.

Can Digital Gold Be Converted Into Physical Gold?

Yes. With GoldNow, users can redeem physical gold after accumulating at least 1 gram in the app. Submit the redemption request through GoldNow and collect the gold from any Tomei outlet nationwide. Applicable denominations and redemption fees are displayed before confirmation.

Is Gold Better Than A Savings Account?

Gold and savings accounts serve different purposes, but gold may be more effective for long-term value preservation. Inflation can gradually reduce the purchasing power of cash held in ringgit, while gold has historically been used as an inflation hedge. GoldNow gold savings also provides a Shariah-compliant way to accumulate physical gold from small amounts.

Is Gold Better Than A Fixed Deposit?

Gold may offer stronger long-term protection against inflation without relying solely on a fixed return. It can help preserve purchasing power when living costs rise, while offering a low entry barrier and convenient liquidity. With GoldNow, users can start from 0.1 gram and manage or convert eligible gold holdings through the app, subject to the applicable terms.

Is It Wise To Buy Digital Gold Now?

There is no single “ideal” entry time for any market asset. Consider your objective, budget and time horizon.  Regular purchases over time can help mitigate short-term market timing risk, though it cannot eliminate losses during broader market downturns.

Start Your Gold Saving Habit Today!

Gold savings no longer needs a large sum to start. Download GoldNow and set up your first monthly gold-saving goal today, starting with an amount small enough that missing it never feels like a loss, and consistent enough that a year from now, the habit shows in grams saved rather than good intentions.

Download Now: Google Store | App Store

Traditional financial choices often lead Malaysians to place their money into Fixed Deposits. Cash savings lose purchasing power over time because of inflation. Gold holds its value across generations and protects wealth from currency depreciation. You do not need thousands of ringgit to own real gold today. You can build a meaningful gold savings asset by accumulating a fixed physical weight of zero point one gram every single month. Starting small allows you to build a permanent financial habit without straining your monthly budget.

Overcoming Malaysia’s Affordability Gap: The Power of 0.1 gram Monthly

Success in personal finance comes from 80% habit and 20% luck. A routine of saving zero point one gram of gold makes wealth accumulation accessible to every salary earner. This small monthly amount removes the fear of high upfront costs. Over a ten-year horizon, small gold savings consistently outpace currency savings. You protect your future financial obligations from the decay of inflation.

Historical data shows that gold savings systematically outperform twelve-month Fixed Deposits over time. Parents who save in gold build a stronger safety net for university tuition fees. For example, international undergraduate tuition in the United Kingdom rose significantly in ringgit terms over sixteen years. When measured in gram of gold, the actual cost of that same education fell by 46%. Gold protects your family from currency fluctuations when financing overseas education.

Medical inflation and rising healthcare costs also threaten long-term cash savings. Gold savings historical growth outperforms standard insurance premium increases. Cash savings in a Fixed Deposit account cover only a small fraction of long-term medical cost inflation. Accumulating gold preserves your healthcare purchasing power. You ensure your medical fund keeps pace with real-world hospital charges.

Lifestyle milestones and spiritual journeys become easier to fund through gold savings. The ringgit cost of standard Umrah travel packages rose by over 60% over ten years. The cost of the same pilgrimage package fell by 55% when priced in gram of gold. Saving in physical weight ensures your money retains its real-world booking power. You achieve your milestones faster by focusing on gold weight instead of cash totals.

The Smart Strategy of Saving in Gram Beats Saving in Ringgit

Financial experts choose to accumulate a fixed physical weight instead of a fixed fiat currency amount. Buying zero point one gram every month applies the principle of Dollar Cost Averaging (DCA) automatically. You buy less gold when prices are high and more gold when prices drop. This method removes the stress of trying to time the financial market. Your total asset value gains strength as you accumulate more weight over time.

You can maximize your wealth by setting up multiple distinct savings targets simultaneously. Dedicate one savings target for a tertiary education fund. Create a separate savings target for future medical expenses. Set up a third savings target for travel milestones or emergency funds. Separating your gold assets into specific targets keeps your financial plan organized and disciplined.

What a Small Monthly Habit Adds Up To Over Time
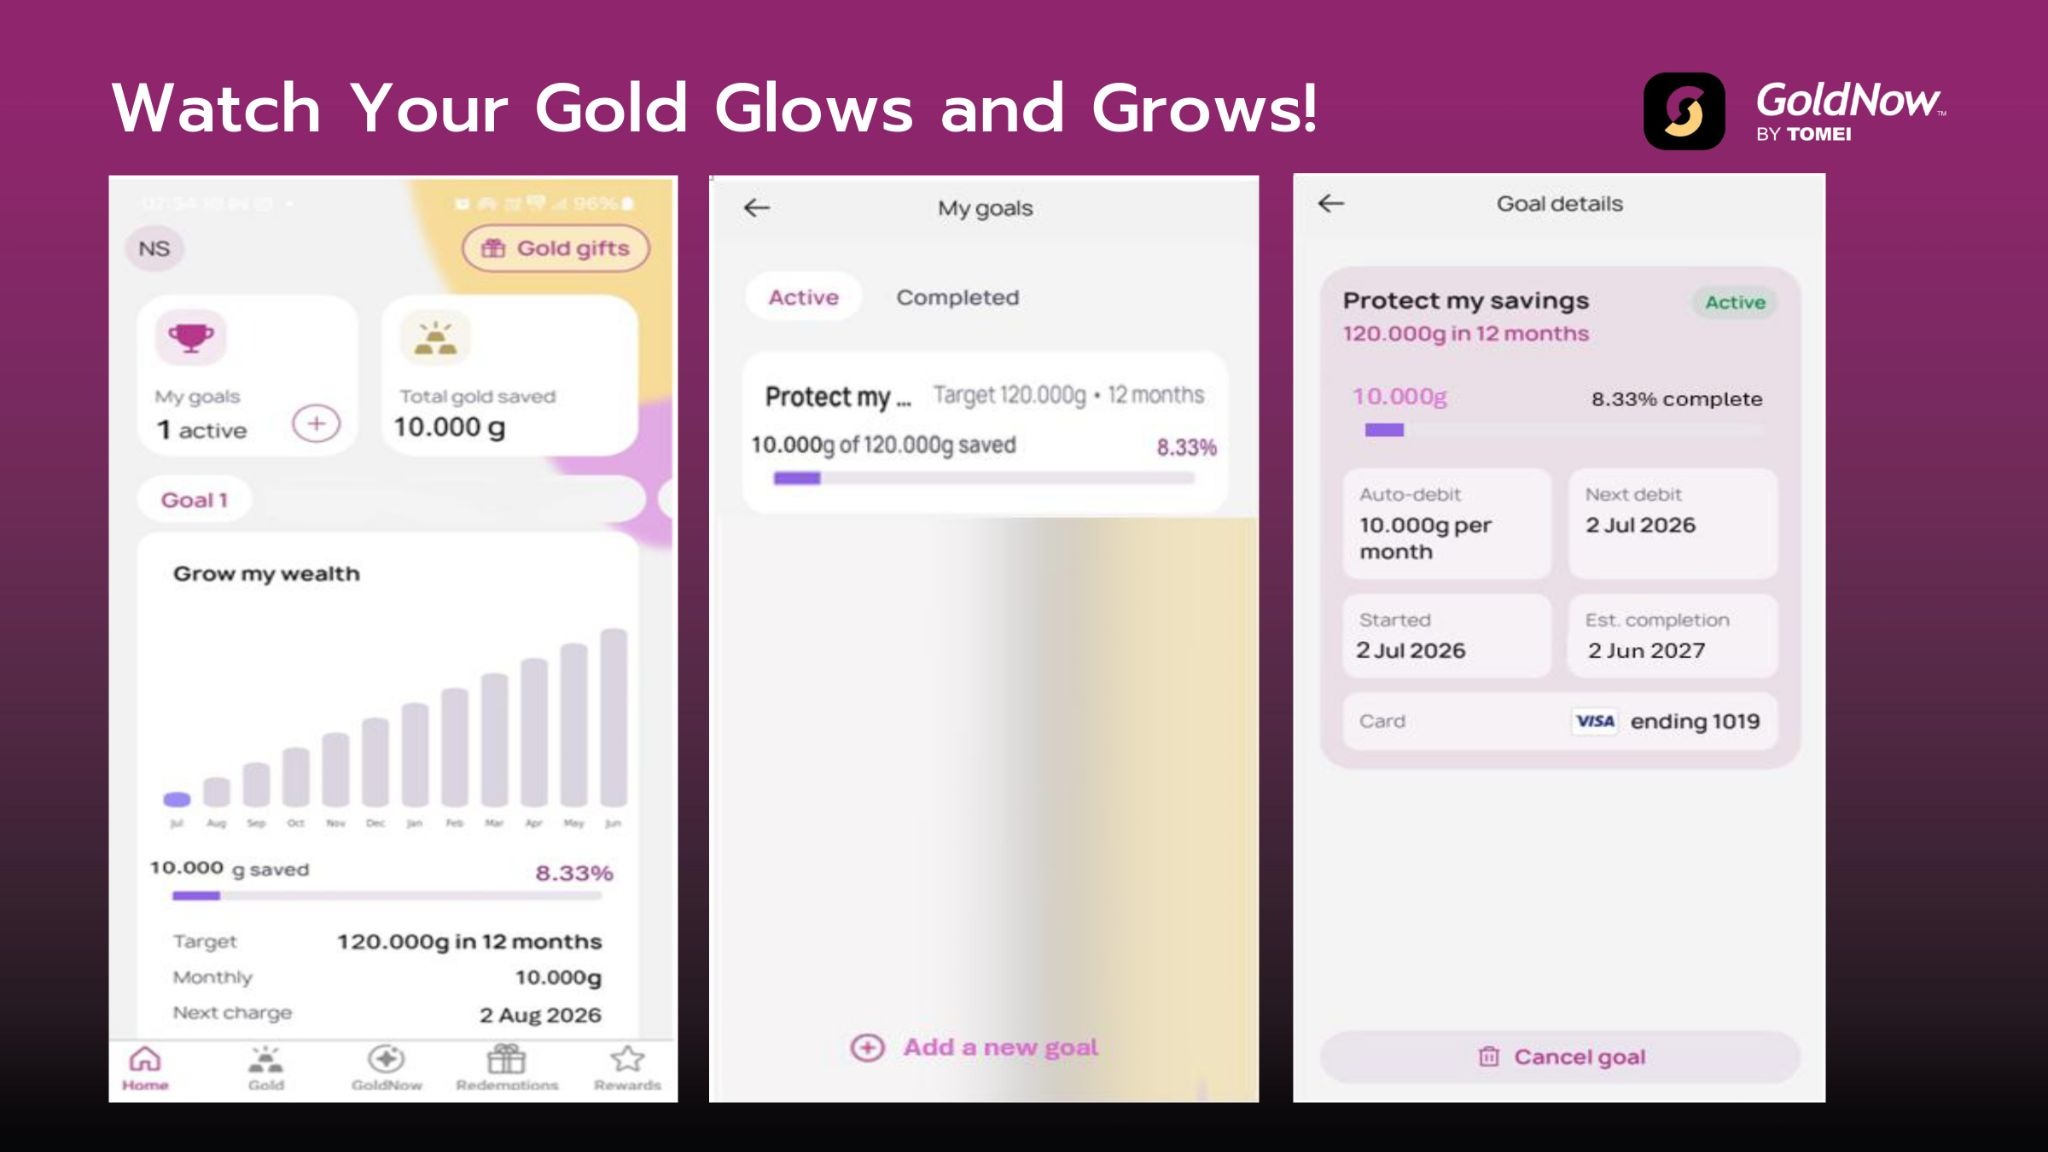
Saving 0.1 gram a month may look small in isolation, yet consistency compounds the same way any habit does. Over 12 months, that pace builds to 1.2 gram saved without a single large payment at any point along the way. Over several years, the same small monthly habit adds up to a meaningful amount of gold, built entirely from amounts too small to notice missing from a monthly budget.

The exact gram accumulated depend on how much you choose to save each month, and gold prices change over time, so the ringgit value of any saved amount moves with the market. This is knowledge sharing to illustrate how a habit builds over time, not a projection of future returns, and you should use your own judgement when setting a saving target.

Reviewing your goal every few months, adjusting the monthly amount up as your budget allows, keeps the habit growing without ever feeling like a stretch.

Introducing GoldNow by Tomei as Your Digital Gold Gateway
GoldNow, backed by Bursa Malaysia-listed Tomei with over 50 years of retail legacy, offers secure digital access to 999.9 pure physical gold. You own real gold without home storage risks.

The platform follows strict security and compliance standards, digitally allocating every grain of gold to physical bullion for complete transparency. Features include:

  • ISRA-certified Shariah compliance, ensuring transactions align with Islamic financial principles.

  • Unused cash kept in a regulated Trustee Bank Account, separate from operational funds.

  • Bullion stored in high-security commercial vaults with insurance coverage against fire, flood, theft, and burglary. For more details, please refer to our official FAQ page.

  • Transparent pricing with clear costs shown upfront, so you know the details before making a purchase or transaction.

How to Set Up a Monthly Gold Saving Habit in the GoldNow App

Setting up a monthly gold saving goal in GoldNow takes a few steps, all inside the Save tab of the app.

  • Create Your Goal.
    Open the Save tab and tap Create My First Goal. Give the goal a name, something like Protect My Savings or Emergency Fund, so it stays clear what the gold is building toward. Naming the goal keeps the habit tied to a purpose rather than sitting as an abstract number in the app.
  • Set Your Monthly Amount.
    Choose how many gram to save each month, starting from a small figure like 0.1 gram, and select a charge day, the date each month the app processes your saving purchase automatically. The app shows the estimated ringgit cost per month based on today’s price, so you know exactly what to expect before confirming.

  • Set Up Auto Debit.
    Link a debit or credit card for recurring payment, and the app charges the same gram amount each month, adjusting the ringgit cost slightly with the daily gold price rather than asking you to calculate anything yourself. From here, the goal runs on its own, saving your set gram amount every month until you reach your target or choose to stop.

  • Run More Than One Goal.
    GoldNow supports multiple goals running at the same time, so a monthly saving habit for one purpose does not need to compete with a separate goal for another, education fund, medical fund, or any target you want to track apart from the rest.

Step-by-Step Guide to Automate Your Gold Savings Plan

Setting up your gold savings plan takes minutes via smartphone. Register digitally using e-KYC verification and link your bank account for secure transfers.

Fund your balance using online banking via FPX. Then, open the goal-setting module to select a monthly weight target and purchase date.

The system automatically buys 0.1 gram on your chosen date, tracking progress on your dashboard. Automated payday saving maintains discipline and builds lasting household wealth.

Moving from Accumulation to Tangible Value

Digital savings can be converted into physical gold bars or dinars and redeemed at over 50 retail outlets across Malaysia. This offers digital flexibility with physical security.

You can also send fractional gold gifts from 0.1 gram to family or clients via a secure link, offering a meaningful alternative to cash.

Protect your purchasing power by building a consistent gold saving habit starting with just 0.1 gram today!

Why GoldNow Is the Best Way to Gold Saving: Backed by Tomei’s Physical Gold Reserves and ISRA Endorsed Shariah Compliance

Backed by Tomei, 50+ Years of Gold Expertise

Every gift sent through GoldNow carries the backing of Tomei, a name Malaysians have trusted for gold and jewellery for over 50 years. Tomei is listed on Bursa Malaysia and operates more than 50 outlets across the country, giving recipients a real place to redeem gold gifts as physical bars or coins whenever they choose.

GoldNow itself holds Shariah-compliant status, endorsed by ISRA, voted the best Shariah finance advisory firm in 2024. Every gram sent through a gift is allocated and stored securely, insured in full, with no hidden fees attached to receiving or holding it. For a gift meant to represent something lasting, that backing matters as much as the gold itself.

How to Redeem a Gold Gift

Redeeming a gold gift works the same way as redeeming any gold held in the GoldNow app. Head to the Redemptions section, choose the amount to convert, and select a nearby Tomei outlet. The gold gets prepared as a physical bar or coin ready for collection, or you leave it saved digitally to keep growing your balance instead. Both the sender and recipient receive a notification the moment a gift moves from unclaimed to claimed, closing the loop without either side needing to check in manually.

FAQ – Gold Savings with GoldNow

What is the minimum amount to start saving gold with GoldNow?

You can purchase gold from 0.1 gram, giving you the flexibility to start with an amount that fits your budget.

How do I change my monthly gold saving amount?

You adjust the gram amount, timeline, or charge day for any active goal directly inside the Save tab.

Is gold saving in GoldNow Shariah compliant?

Yes, GoldNow holds Shariah-compliant status endorsed by ISRA, and every gram saved follows the same compliance standard as gold bought directly.

How do I redeem my saved gold?

Saved gold redeems as a physical bar or coin at any Tomei outlet, or stays saved digitally if you prefer to keep building your balance.

Start Your Gold Saving Habit Today!

Gold savings no longer needs a large sum to start. Download GoldNow and set up your first monthly gold saving goal today, beginning with an amount small enough that missing it never feels like a loss, and consistent enough that a year from now, the habit shows in gram saved rather than good intentions.

Download Now: Google Store | App Store

Secret Link